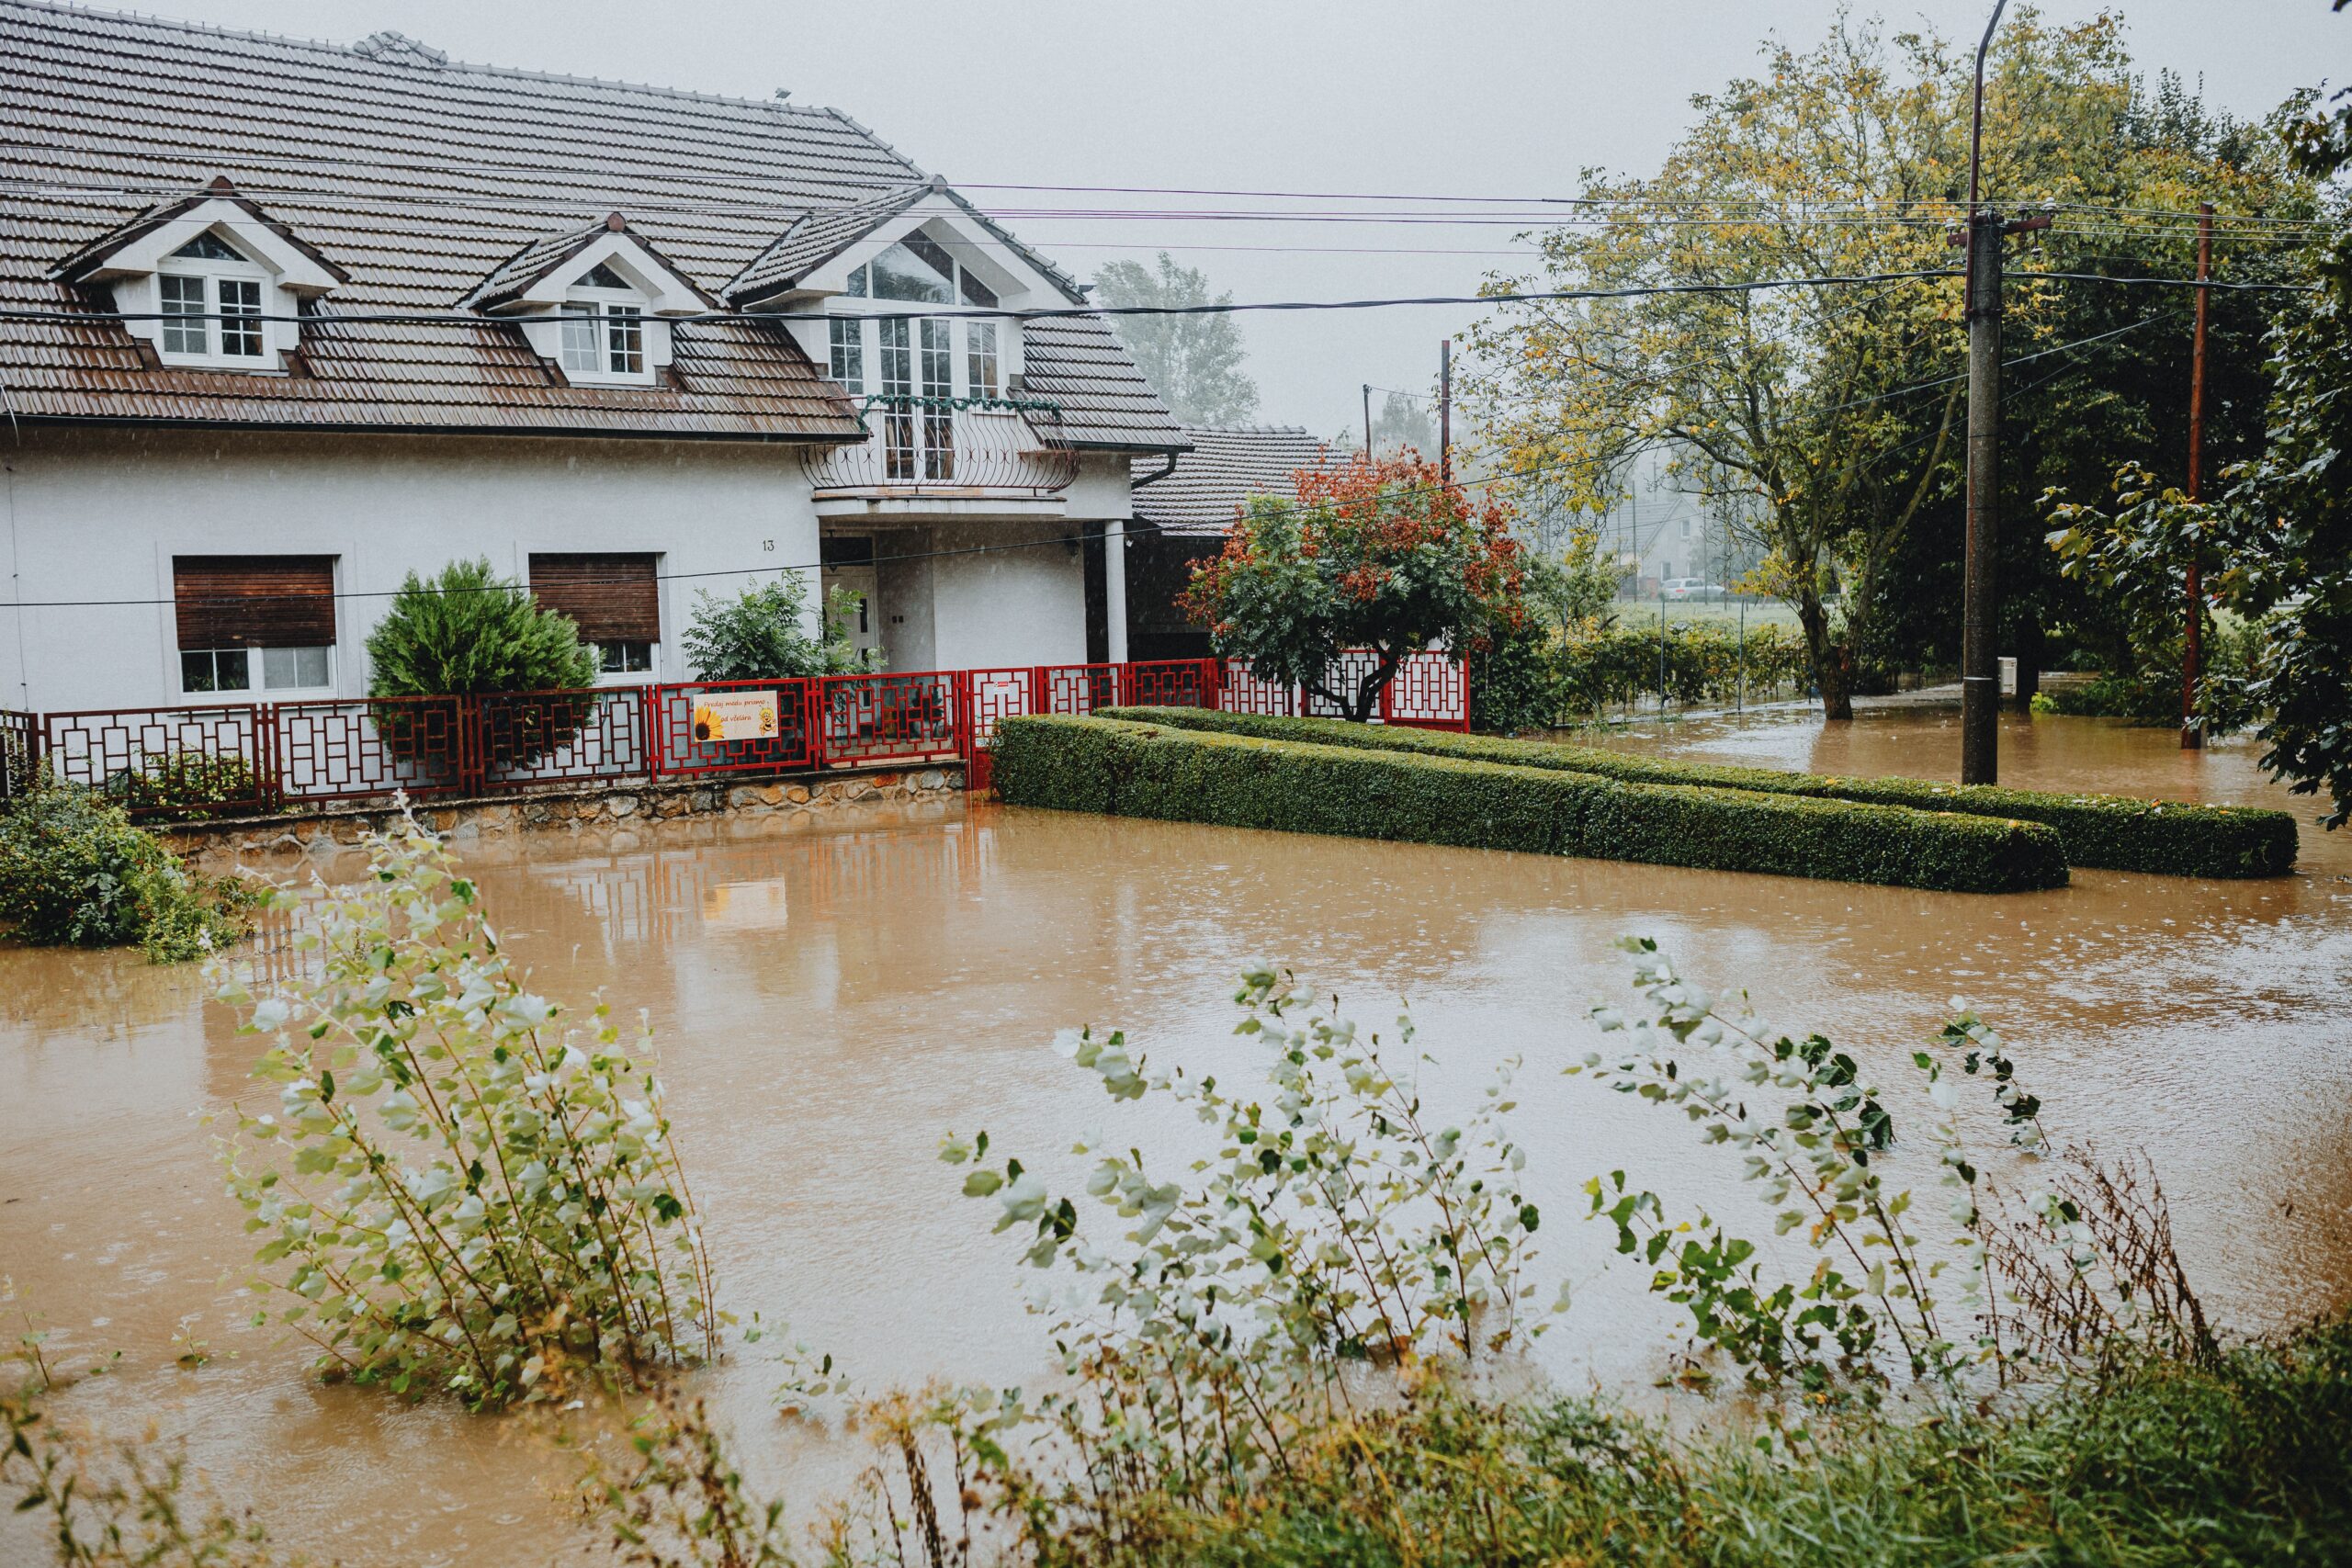

Flooding poses a severe financial threat to homeowners through structural damage and costly repairs. Many property owners rely on government-backed protection, but private carriers offer flexible alternatives built around specific risk profiles and coverage requirements. At Flood Insurance HQ, we help property owners explore tailored policy options and secure competitive pricing. We also protect valuable real estate assets against unexpected losses. Our guide breaks down operational mechanics and cost factors. Furthermore, it details the structural advantages of a private flood insurance coverage policy to help select the right safeguard for your property.
What Defines Private Flood Insurance?
Independent insurance companies underwrite, manage, and financially back private flood insurance policies rather than government entities. Unlike traditional policies issued through the National Flood Insurance Program (NFIP), private options provide customized protection designed to meet individual homeowner needs. Private insurers utilize mapping technology and property data to assess risk levels. Additionally, carriers apply localized risk modeling to calculate premiums based on exact property structures rather than broad regional designations. Homeowners comparing options often review top private flood insurance companies to find flexible limits for building structures and personal belongings.
These independent policies feature broader limits for building structures alongside personal belongings. In addition, policies cover extra living expenses during displacement. For homeowners seeking higher coverage limits or quicker effective dates, private options deliver an adaptable alternative to rigid federal guidelines. Homeowners can add specialized policy riders to expand overall structural protection.
How Does Private Flood Coverage Operate?
Private flood protection functions similarly to standard homeowners insurance policies through an individual contract between the property owner and the insurer. The carrier assesses the property address, elevation, and structural materials. Furthermore, underwriters analyze historical water damage data to construct a flood insurance policy with precise limits and deductibles.
When a covered water event damages a building or its internal contents, the policyholder submits a formal claim directly to the insurer. An adjuster evaluates physical damage before calculating repair costs. Next, the adjuster calculates content replacement values to process payouts based on agreed policy terms.
Key operational features of private coverage include:
- Flexible limit options exceeding federal maximum payouts
- Custom deductible structures tailored to personal financial preferences
- Shorter waiting periods before coverage takes effect
- Optional coverage for loss of use and temporary living accommodations
Looking for faster flood coverage with zero waiting periods?
What are the Key Differences Between Private Insurance and the NFIP?
Choosing the right policy requires comparing independent insurance products against federal standards. The main distinctions center on coverage thresholds, waiting periods, content limits, and supplemental living expenses.
-
Structural and Content Coverage Limits
The NFIP caps residential building coverage and personal contents protection. These limits frequently fall short for higher-value homes or properties containing expensive inventory. In contrast, private carriers regularly offer building coverage exceeding several million dollars, along with expanded protection for personal possessions.
-
Policy Effective Dates and Waiting Periods
Standard federal policies require a mandatory 30-day waiting period before protection takes effect. This delay leaves properties vulnerable during active storm seasons. In contrast, private options feature much shorter waiting periods. Policy activation ranges from immediate coverage to a 14-day delay. It enables faster protection when buyers close on real estate purchases or prepare for upcoming weather events.
-
Temporary Living Expenses and Additional Coverage Options
Federal policies do not reimburse homeowners for temporary housing or extra living expenses if a home becomes uninhabitable. Private contracts frequently include loss-of-use coverage for families during displacement. These funds reimburse expenses for temporary hotel stays, dining, and storage facilities while contractors repair water damage. Obtaining accurate private flood insurance quotes allows property owners to evaluate these helpful supplemental benefits alongside standard structural protections.
How Do Premiums and Costs Get Calculated?
Insurers evaluate multiple data points to compute risk scores and monthly premiums. Because private entities use proprietary underwriting software, rate structures vary significantly across providers based on geographical factors and structural traits.
Major rate drivers include:
- Structural elevation relative to base flood elevations
- Foundation types, including crawl spaces, basements, or raised pilings
- Construction materials used in the building frame and exterior walls
- Specific geographic proximity to coastal areas, lakes, and rivers
- Historical water damage records and past claims submitted for the property
Understanding your property’s precise flood zone designation allows carriers to deliver accurate premium pricing reflecting actual environmental risk levels rather than generalized region-wide metrics.
Who Benefits Most From Private Coverage Options?
While government-backed protection suits certain standard real estate profiles, private protection delivers distinct advantages for specific homeowner categories.
- High-value homeowners requiring property limits above $250,000
- Real estate buyers needing immediate policy activation to complete property closings
- Property owners seeking loss-of-use reimbursement for temporary living arrangements
- Property owners residing in mid-to-low risk zones looking for competitive rating structures
Reviewing options through established private flood insurance companies ensures property owners find policies that fit specific architectural designs, structural modifications, and financial plans.
How to Obtain and Choose the Best Policy?
Securing effective property protection requires analyzing coverage terms, calculating replacement costs, and reviewing specific deductible options carefully. Working with our team simplifies evaluating carrier policies against federal limits.
To secure an optimal policy:
- Gather essential property information, including foundation types, construction details, and elevation metrics.
- Review total asset values to determine accurate building and contents coverage requirements.
- Compare policy exclusions, deductibles, loss-of-use allowances, and pricing options.
- Secure an active flood insurance policy before high-risk storm seasons or property purchase closings begin.
Ready to safeguard your property investment against unexpected water damage?
Contact Flood Insurance HQ Today
Securing Complete Financial Protection for Your Property
Protecting residential property against unpredictable weather demands comprehensive coverage built around exact structural designs and property values. Our independent policy options offer higher coverage limits, necessary loss-of-use benefits, and flexible deductible structures matched to individual budget goals. As one of the leading flood insurance companies, Flood Insurance HQ provides clear guidance, direct answers, and dependable financial protection against sudden water damage. Homeowners can secure their property today by reviewing our tailored coverage options designed for their specific housing needs.
Frequently Asked Questions
-
What exact protections does private flood insurance coverage deliver?
Comprehensive private flood insurance coverage protects primary building structures and foundational elements. Policies cover essential mechanical systems, detached garages, and personal belongings. Insurance carriers process claims for structural restoration alongside interior wall remediation. Additionally, policies cover electric panel repair and appliance replacement after rising water incidents. These funds provide financial assistance while contractors repair flood-damaged living quarters.
-
How do property owners generate private flood insurance quotes quickly?
Generating private flood insurance quotes requires submitting essential property information. Applicants supply the building location, foundation layout, and primary construction material classifications. Insurance specialists process geographical terrain data alongside neighborhood drainage characteristics. Specialists also review property elevation credentials. The review addresses structural risks and coverage parameters without processing delays.
-
Why do homeowners select private flood insurance companies over government options?
Property owners choose independent private flood insurance companies to secure higher coverage limits. Policyholders gain faster policy activation alongside broader protection terms. Private carriers offer higher payout ceilings for high-value properties. Policies include loss-of-use compensation managed through modern risk modeling. These detailed mapping systems often yield lower premium rates.
-
Which specific factors determine the total price of a flood insurance policy?
Foundation architecture and exterior building materials dictate base rates. Regional weather patterns and structural elevation relative to water sources shape the cost of a flood insurance policy. Choosing higher deductible amounts reduces annual premium expenses. Adding supplementary coverage options increases the overall insurance investment. Higher personal content limits or loss-of-use protection expand total policy value.
-
Does a property’s flood zone designation restrict private carrier availability?
A high-risk flood zone designation does not prevent independent insurers from underwriting residential coverage. Private insurance carriers evaluate properties across all risk tiers. Insurance companies cover high-risk coastal zones alongside low-risk inland locations. Utilizing granular topographical mapping tools rather than broad municipal boundaries improves precision. Underwriters deliver tailored policy options regardless of official local flood zone classifications.