
Flood risks in Florida are among the most difficult in the whole country, and the designation of a severe repetitive loss property will affect the way the policy will be maintained and even the price for maintaining such a policy. At Flood Insurance HQ, we will try to guide the Florida homeowner about the implications of this designation and what can be done in order to avoid any problems that may come up with the home.
What Is a Severe Repetitive Loss Property?
A severe repetitive loss property refers to an NFIP-covered property that has suffered severe claims from flooding over time. The NFIP normally defines a property as being a severe repetitive loss property if it has experienced four or more separate payments of claims worth more than $5,000, totaling $20,000 or above, or if two separate building coverage payments are above the market value of the structure.
Two or more qualifying claims should have been made within the last 10 years, with the claims occurring at least 10 days apart. The history of claims on the property is evaluated since the year 1978 or since its construction if the structure was constructed after 1978, irrespective of the owners of the structure during that period.
This is contrary to what happens in repetitive loss properties, whereby there are two or more claims within 10 years, above $1,000. This is how we do things at Flood Insurance HQ.
Worried about how repeated flood claims will change your flood insurance?
Why a Repetitive Loss Property Florida Home Receives This Designation
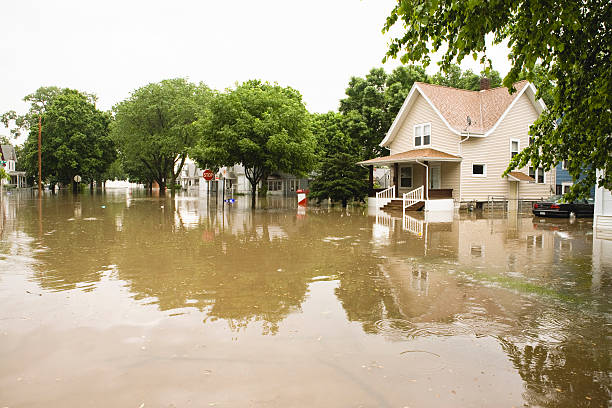
Due to the combination of factors such as the state’s long coastline, low elevations, high rainfall levels, hurricanes, and outdated drainage systems, a repetitive loss property in Florida might face storm-surge damage from one hurricane season and freshwater flooding in the next season due to heavy rainfall. This process is bound to happen over time to become severe repetitive loss.
The severe repetitive loss status is tied to the building itself and not the owner. What this implies is that a new owner of the property is likely to inherit the claim history regardless of whether they contributed to previous losses or not. In this regard, we recommend that buyers in Florida do some background checks about the property’s claim history, its elevations, and floodplains before acquiring it.
Severe repetitive loss status impacts various aspects of homeownership, including lending policies, resale negotiations, and eligibility for mitigation aid. However, a property with this classification is not necessarily uninsurable, but only requires a better risk management approach.
How FEMA Repetitive Loss Rules Affect Your Policy
When a home receives the severe repetitive loss designation, its NFIP policy is generally transferred to the Special Direct Facility, FEMA’s servicing arm for these higher-risk properties. FEMA repetitive loss rules may lead to a premium increase intended to reflect the property’s elevated flood risk, along with a 15% severe repetitive loss surcharge applied at the next renewal after designation.
This does not mean coverage disappears. The NFIP can still renew coverage through the Special Direct Facility, but the process and pricing may differ from a standard policy. At Flood Insurance HQ, we help homeowners review their current coverage, explain the notice they receive, and identify whether mitigation or alternative coverage options may make sense.
What Multiple Flood Claims Mean for Your Home
Multiple flood claims are often the reason a property becomes a severe repetitive loss property. FEMA looks at the building’s full claim history, including claims made by previous owners, so a home can receive the designation even if the current owner has never filed a claim.
After the designation, FEMA or the NFIP typically notifies the policyholder, insurance agent, and lender before the policy renewal. The notice explains that the property has been identified as severe repetitive loss and that future NFIP coverage must be issued and serviced through the Special Direct Facility.
Homeowners should not ignore this notice. It is an opportunity to confirm the claim history, ask questions about the classification, and begin planning mitigation before the next renewal.
What Flood Insurance HQ Recommends
At Flood Insurance HQ, it is our firm belief that being tagged as a severe repetitive loss is an occasion that calls for action rather than panic. Our staff will assist Floridian homeowners in checking their insurance claims history, comprehending the notice of designation, evaluating available insurance coverages, and linking flood-risk reduction efforts with insurance coverage.
Our advice is to begin by following three initial steps: obtaining a certified copy of the loss history of the property, getting a flood zone insurance quote in the current zone and level of protection, and talking to the floodplain manager or mitigator about suitable measures that can be undertaken.
Thus, a severe repetitive loss property can be improved and covered. It is only necessary for the property owner to take it as a sign and act accordingly.
Need help protecting your Florida home from future flood losses?
A Severe Repetitive Loss Property Needs a Clear Plan, Not Panic
Even though the severe repetitive loss designation is a serious matter, it does not necessarily mark the end of the line for a homeowner in Florida. This signifies that there is a history of losses due to flooding and there is now a strong rationale to examine your coverage options for property insurance in Florida and other related things. Here at Flood Insurance HQ, we help you with the FEMA requirements for repeated losses.
Frequently Asked Questions
-
What qualifies a home as a severe repetitive loss property?
A severe repetitive loss property is an NFIP-insured home with either four or more claims over $5,000 totaling more than $20,000, or two building claims whose combined payments exceed the building’s market value. At least two claims must fall within 10 years and occur more than 10 days apart.
-
Does a repetitive loss property Florida designation stay after sale?
Yes. FEMA reviews the property’s flood claim history since 1978, regardless of ownership changes. A repetitive loss property Florida buyer inherits the designation and loss history, which is why buyers should review NFIP claim records, elevation information, and local floodplain requirements before purchasing.
-
Can a homeowner dispute a FEMA repetitive loss classification?
A homeowner can request a review if they believe the claim history or FEMA repetitive loss designation is incorrect. Supporting documents may include claim records, payment details, dates of loss, and property information. Because FEMA counts losses across prior ownership, accurate documentation is essential when asking for a reassessment.
-
What mitigation projects help after multiple flood claims?
Common options include elevating the home, relocating the structure, acquiring and converting the property to open space, or dry floodproofing eligible historic buildings. After multiple flood claims, elevating utilities, improving drainage, and using flood-resistant materials can also reduce future damage, though eligibility and requirements vary by program and location.
-
How does this affect a flood zone insurance quote?
A severe repetitive loss property may receive higher NFIP pricing through the Special Direct Facility and a 15% surcharge after designation. A flood zone insurance quote should account for the property’s claim history, elevation, flood zone, coverage limits, and any completed mitigation, since these factors can materially affect cost and eligibility.


