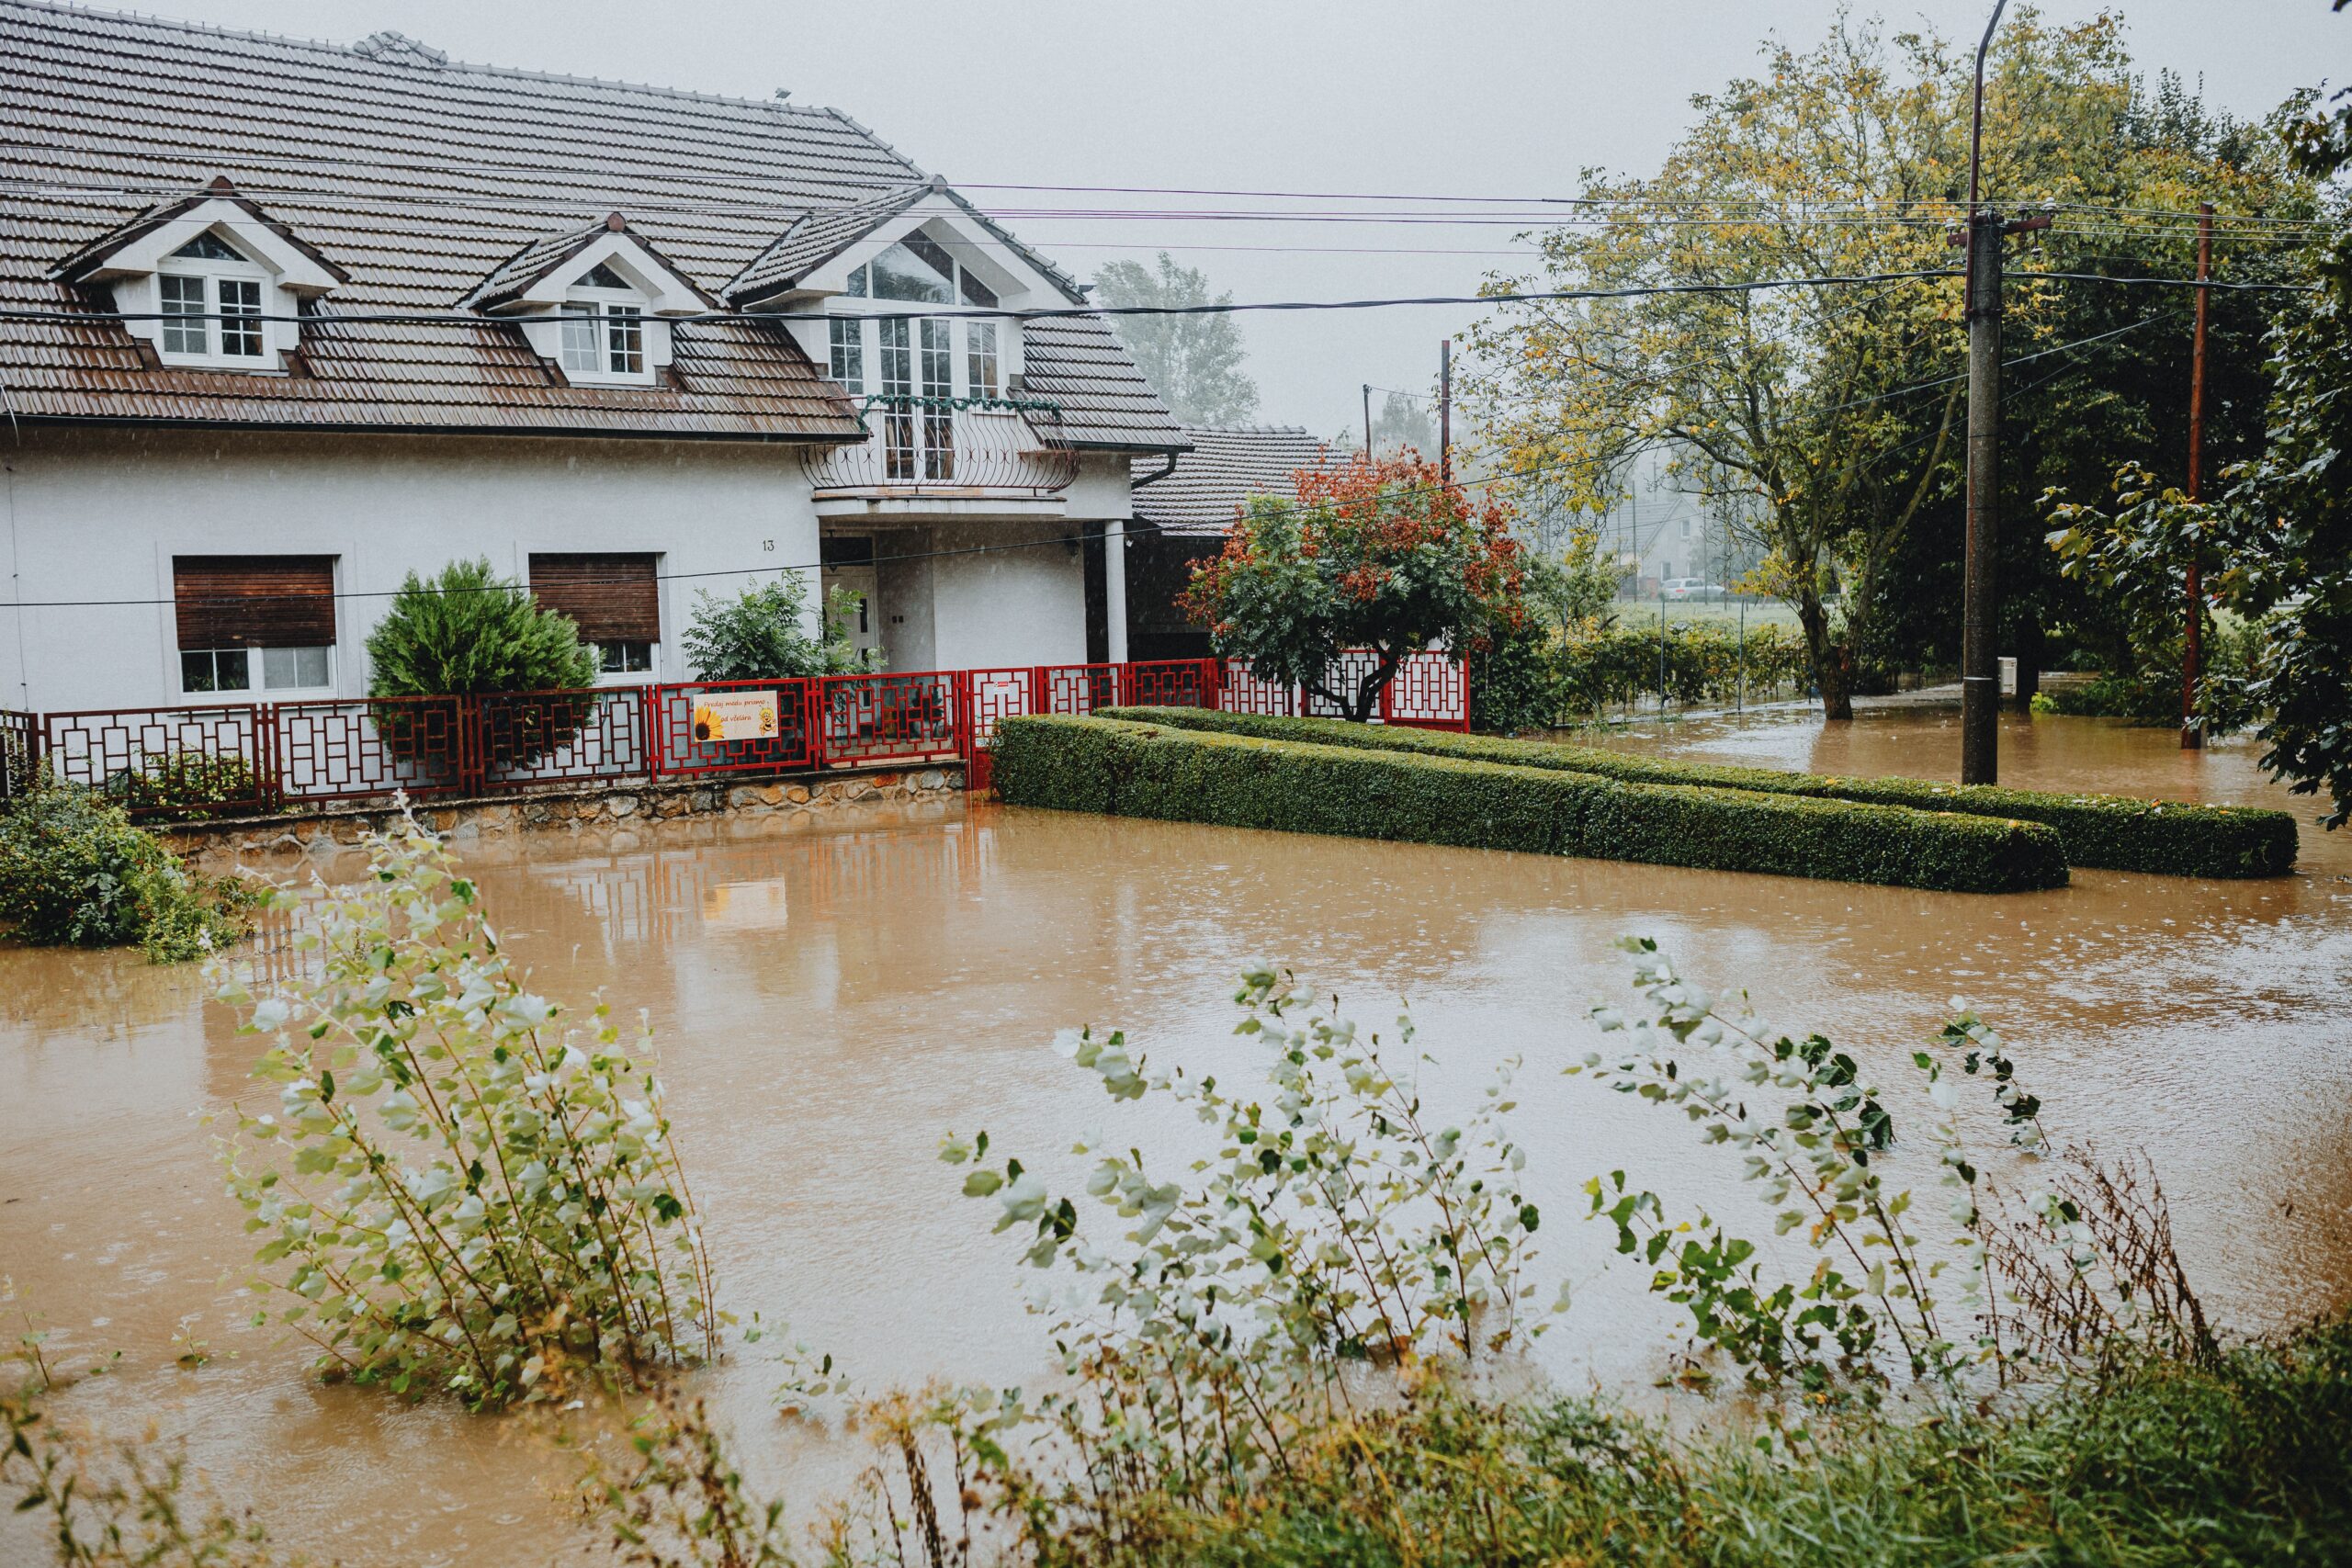

Standard home policies leave out water damage from rising streams, ocean surges, or backed-up city drains. Getting clear protection means dealing with official rules, property elevation records, and different policy types. At Flood Insurance HQ, our team makes this process simple by checking physical building risks, comparing federal and independent choices, and setting up a plan that fits your spending limits. Working with a local flood insurance agent gives homeowners direct access to local storm knowledge and practical policy options that guard against high costs after sudden storms.
What Role Does an Agent Play in Risk Assessment?
Checking real property risk forms the basis of picking proper flood protection. A skilled representative looks at your exact property lines and home design instead of relying on basic neighborhood maps.
- FEMA Map Analysis: Professionals check current Flood Insurance Rate Maps to see if your building sits in high-risk areas like Zone A or V, or lower-risk areas like Zone X.
- Elevation Data Review: Reps review foundation styles like concrete slabs, crawlspaces, or raised stilts and check Elevation Certificates to measure where your lowest floor sits compared to flood levels.
- Historical Water Data: Looking at local water flow, past storm surge records, and nearby water movement reveals hidden threats that basic map lines skip over.
By doing deep risk checks, flood insurance agents make sure homeowners never lack critical coverage or pay extra fees for unneeded add-ons.
Is your current flood policy enough to cover total rebuilding costs?
Compare Flood Coverage Options
How Do You Navigate National and Private Options?
Choosing between federal programs and non-governmental options is one of the most critical decisions in securing your property.
The National Flood Insurance Program (NFIP), managed by FEMA, provides government-backed protection with standardized terms across participating communities. However, the NFIP caps residential building protection and contents coverage limits.
Alternatively, private flood insurance policies often deliver significantly higher limit caps, shorter waiting periods, and expanded protection features. An experienced policy representative balances these frameworks against your mortgage lender requirements and financial tolerance.
Why Is Customizing Property Protection Vital?
Every residential structure contains distinct physical elements and high-value possessions that require custom policy parameters. Selecting arbitrary coverage figures can leave major financial gaps during a major water intrusion event.
- Building Structure Protection: Policy limits must match the true cost of rebuilding your home’s framing, foundation, plumbing, wiring, central AC, and built-in appliances.
- Belongings and Contents: Getting personal property coverage makes sure your furniture, clothes, TVs, and decor are paid out fairly using Actual Cash Value or Replacement Cost Value.
- Detached Structures: Unattached buildings like guest homes, detached garages, or sheds need specific policy add-ons so they do not get left out of your main plan.
A dedicated flood insurance specialist meticulously audits these individual categories to prevent major gaps between your actual loss and insurance reimbursement limits.
What Additional Protections Belong in Your Policy?
Standard flood insurance handles major structural fixes and cleanup, but extra post-storm bills add up fast without the right coverage add-ons in your policy.
- Additional Living Expenses Protection: Temporary living costs like hotel stays and meals add up fast during repairs. We help you secure Loss of Use benefits through independent carriers to cover these daily expenses.
- Increased Cost of Compliance Coverage: Rebuilding often means following new local building codes. This add-on provides extra funding to elevate or modify your home to meet updated city standards.
- Debris Removal Coverage: Clearing away mud, broken trees, and ruined materials from your yard after a storm carries heavy contractor fees. This protection covers extra cleanup costs so your property gets cleared quickly.
How Can Agents Help Reduce Expenditure?
Lowering your yearly flood insurance costs takes strategic planning and smart property updates rather than taking on high out-of-pocket deductibles.
- Flood Vent Installation: Adding flood vents in crawlspaces or garage walls lets water pass through safely. This relieves wall pressure and earns you direct rate discounts on your policy.
- Essential Equipment Elevation: Raising central AC units, water heaters, and breaker panels above flood levels protects critical equipment. This update lowers your property risk and helps cut annual premiums.
- Elevation Certificate Verification: Checking or updating your official property elevation records can correct inaccurate risk tiers. Showing your home sits higher than basic maps claim can significantly trim yearly rates.
- Annual Policy Reviews: Town drainage updates and map changes can alter your official risk zone. We review your policy yearly to catch community upgrades that lower your insurance costs.
Ready to shield your home against unpredictable Florida water damage?
Connect With Flood Insurance HQ For Complete Protection
Finding complete financial security against unpredictable storm surges and surface flooding requires expert insight, comprehensive risk analysis, and tailored policy options. At Flood Insurance HQ, our dedicated team helps you evaluate building structures, compare government-backed programs against independent market choices, and customize coverage limits to safeguard your estate completely. Rather than navigating complex rating tables and endorsement forms alone, let our specialists construct a resilient safety net for your property. Connect with top flood insurance companies in Florida today through Flood Insurance HQ to secure reliable coverage that fits your needs.
Frequently Asked Questions
-
How does a local flood insurance agent determine flood policy rates?
Evaluating property risk requires analyzing official FEMA flood maps, structural elevation data, foundation types, and proximity to regional water bodies. A local flood insurance agent reviews local topographic features against government schedules and independent market underwriting guidelines. This direct technical analysis ensures appropriate risk classification, accurate rate calculations, and well-structured financial protection for structural investments.
-
What factors cause variance among flood insurance agents’ quotes?
Discrepancies among policy quotes stem from distinct underwriting standards, selected deductibles, policy endorsements, and insurer market access. Certain flood insurance agents leverage relationships with independent underwriting firms offering specialized rating models, whereas other providers rely exclusively on standardized federal program tables. Geographic risk modeling nuances and custom coverage options further create significant variations in pricing structure.
-
Why consult a flood insurance specialist before selecting coverage limits?
Preventing severe financial loss during flood events requires accurate replacement cost estimation and thorough asset valuation. Consulting a flood insurance specialist ensures complete alignment between building valuation, contents pricing, and regulatory program caps. Professional evaluation helps establish necessary coverage limits, identifies critical missing endorsements, and eliminates dangerous financial gaps prior to major disaster occurrences.
-
Which options exist among flood insurance companies in Florida?
Florida homeowners choose between federal National Flood Insurance Program coverage and independent insurance carriers. Top flood insurance companies in Florida offer flexible policy setups, higher structure limits, extra protection options, and shorter waiting periods. Comparing local carriers helps property owners find dependable protection built for specific coastal storm risks and sudden street flooding.
-
How does private flood insurance differ from federal programs?
Independent policies offer higher building limits, flexible deductible options, shorter waiting periods, and extra temporary living cost options. Choosing private flood insurance lets homeowners guard valuable properties past standard federal caps while adding specific extra terms. In contrast, federal plans enforce strict limits, regular thirty-day waiting periods, and single standard protection guidelines.