Skip to content

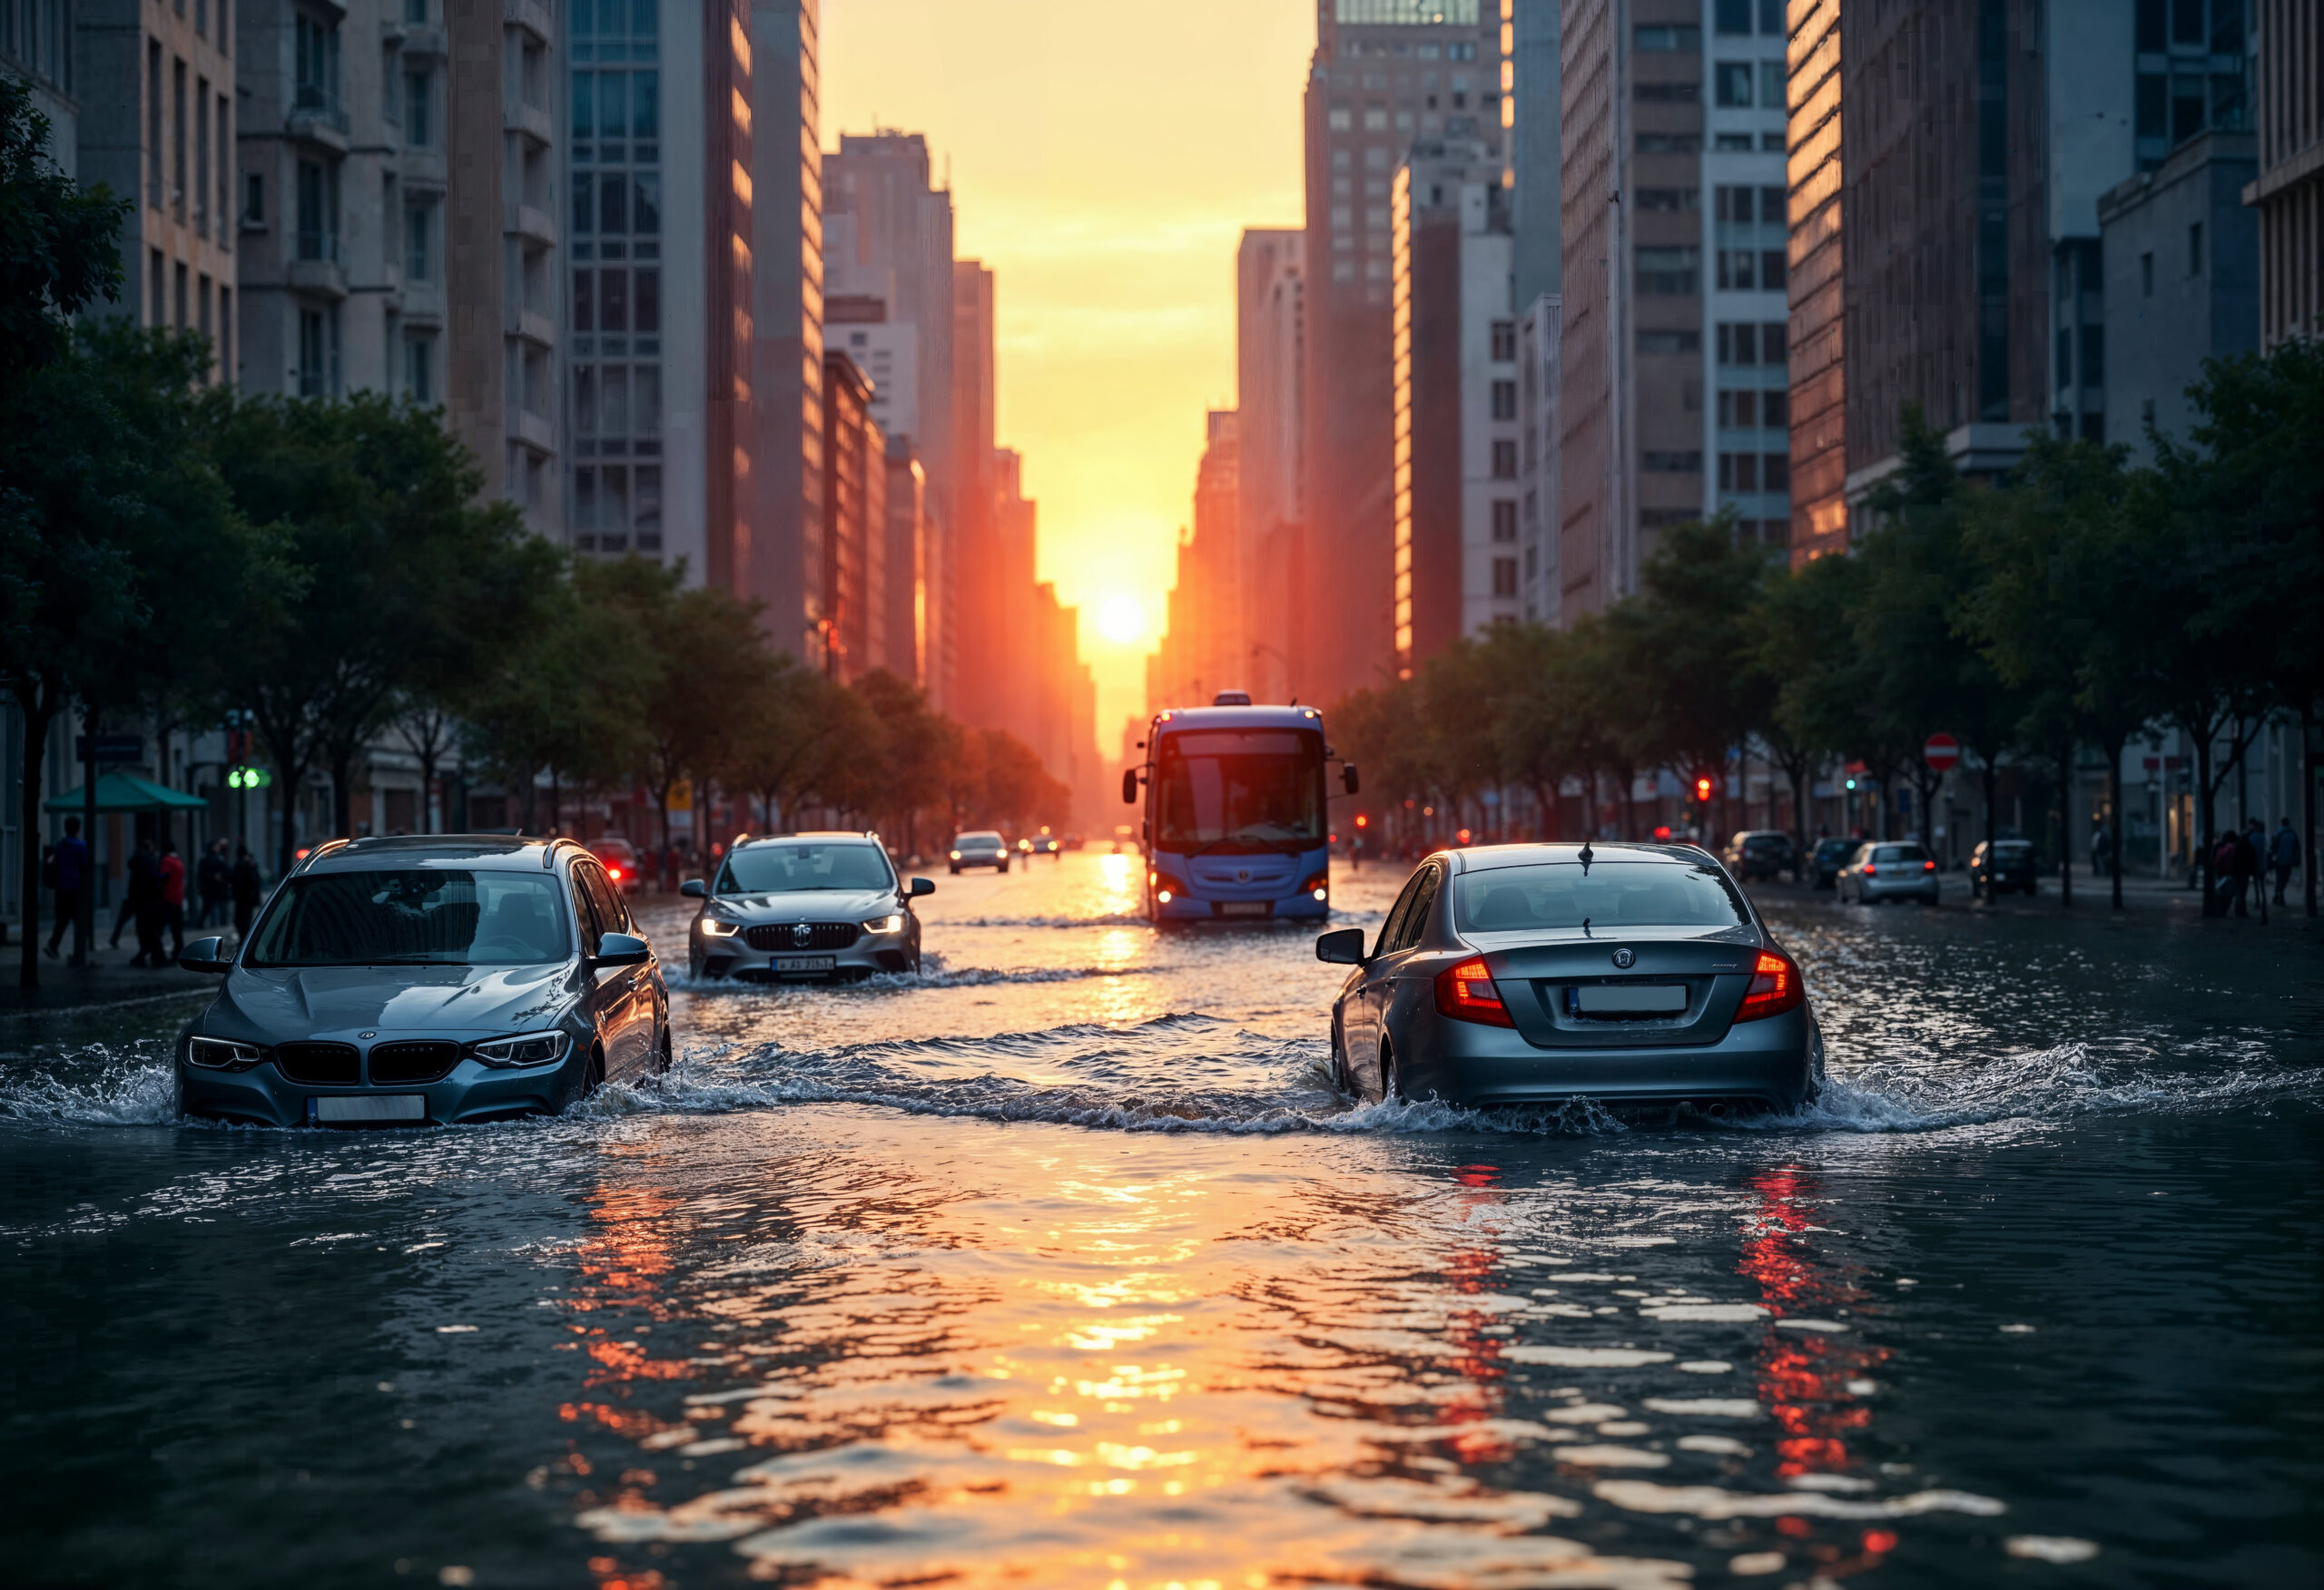
Flooding is one of the most destructive natural hazards in North America. It often causes thousands of dollars in house and property damage within minutes. Standard home insurance policies rarely cover water damage from rising coastal waters, heavy rain, or storm surges. Without extra protection, homeowners face high out-of-pocket costs when disasters hit. Flood Insurance HQ gives expert help to handle these financial risks. We help clients check risk zones, choose between public and private policy options, and pick good coverage limits. Getting reliable flood insurance services in Florida helps homeowners and business owners protect their money against unexpected weather. This guide shows how the right insurance protects home investments and offers stability when recovering from severe weather.
Why Are Standard Homeowner Policies Insufficient for Water Damage?
Standard home insurance covers inside water damage, like broken pipes or leaky appliances, as well as backed-up sewers. Standard policies do not cover rising outdoor water. When heavy rain or full rivers flood a home, standard insurance pays nothing, and coastal ocean surges are not covered either. Fixing house damage without flood insurance means paying with your own money, and buying new belongings is also up to you. High costs can drain savings or force people to take out loans.
Getting full flood protection bridges this coverage gap. Independent flood insurance providers help property owners check their home’s structure. Proper policy checks ensure every square foot gets financial backing before severe storms hit.
Want to protect your home’s foundation and belongings from rising floodwaters?
Get in Touch
How Does Dedicated Coverage Lower Direct Out-of-Pocket Costs?
Fixing water damage requires spending money on many things. These include drying out walls, cleaning mold, fixing drywall, and repairing electrical wiring. Without active flood insurance, a few inches of water can cost tens of thousands of dollars. Having a flood policy lowers these costs by passing the bill to an insurance company.
Having good residential flood insurance means big structural repairs fall under policy limits instead of personal income. Cleaning and replacing home items is also covered under these limits. By picking a good deductible and policy limit, homeowners can manage their monthly budget without fearing sudden, big costs.
Key ways dedicated insurance lowers out-of-pocket costs include:
- Direct payouts for structural fixes and foundation repairs
- Financial coverage to replace ruined home appliances and main systems
- Less need to use high-interest loans or emergency savings
- Faster access to recovery funds right after an official disaster declaration
What Specific Assets Does Structural and Property Protection Cover?
Full flood protection is split into two main insurance parts. These parts are building protection and items coverage. Understanding these two parts ensures physical buildings and personal items get full financial backing.
Building limits protect the foundation, interior walls, and stairs. They also cover plumbing pipes along with central heating or cooling units. On the other hand, items policies cover personal things like furniture, clothes, electronics, and appliances. Picking good building property coverage makes sure house repairs do not take away the money needed to replace personal belongings.
Why Is Evaluating Public and Private Market Options Necessary?
Homeowners can choose between the National Flood Insurance Program (NFIP) and private insurance options. Standard NFIP policies give coverage backed by federal rules. Private insurance companies often offer higher policy limits, money for temporary living costs, and shorter wait times before coverage starts.
Comparing public programs with private insurance choices shows clear benefits:
- Private policies often offer limits that go higher than standard federal caps.
- Federal policies keep fixed rules, while private companies offer add-on choices.
- Private companies can include temporary housing costs in regular claim packages.
- Independent agents check both options to find a good balance between cost and limits.

How Can Proper Policy Preparation Speed Up Disaster Recovery?
Getting policy papers set up before bad weather hits speeds up the money payout process. When floodwaters go down, homeowners with active protection can file claims right away. Adjusters inspect damage and approve claim money.
Fast claim processing lets homeowners hire repair crews early. Starting work early stops mold growth and extra house damage before costs get too high. Quick payouts help people rebuild faster and keep up home value.
Want to safeguard your lifetime property investment before the next big storm hits?
Get Started Today
How to Secure Your Property and Financial Future with Flood Insurance HQ?
Getting proper coverage turns a bad natural disaster into an easy money recovery process. Homeowners use full insurance to protect their home value instead of paying out of pocket for costly repairs, mold removal, and rebuilding. Picking the best policy means checking risk areas and foundation types. Homeowners must understand the differences between government programs and private insurance options. Flood Insurance HQ gives clear help to explain insurance terms, check coverage limits, and get good rates for homes and businesses. Working with the best flood insurance companies in Florida keeps your property safe during bad storms and sudden floods.
Frequently Asked Questions
-
What do flood insurance services in Florida cover?
Comprehensive flood insurance services in Florida safeguard structural components and indoor belongings against sudden water damage. Base plans rebuild walls, repair electrical networks, fix foundations, and restore heating units. Secondary contents protections cover furniture, electronics, and household goods. Selecting balanced policy parameters guarantees financial support for both critical home infrastructure and essential personal property after storms.
-
How do flood insurance providers calculate policy costs?
Underwriters analyze property location, foundation construction, structural elevation, and regional flood risk to calculate policy costs. Proximity to coastline boundaries and selected deductible amounts directly sway pricing decisions. Licensed flood insurance providers examine these technical elements carefully to identify savings opportunities while establishing full building safety and long-term financial stability for every property owner.
-
Why is residential flood insurance essential for homeowners?
Standard property insurance excludes rising natural water damage, creating severe risk for unprotected home equity. Getting residential flood insurance shifts huge cleanup and repair bills onto insurance companies. Moreover, flood policies safeguard savings and prevent high-interest debt. Dedicated coverage guarantees quick access to rebuilding funds after heavy rain or coastal storms. Rapid river flooding falls under policy protections as well.
-
How do higher deductibles influence insurance premiums?
Selecting a larger deductible lowers annual insurance premiums by shifting initial recovery expenses to policyholders during active claims. Out-of-pocket payment obligations increase during losses, yet ongoing yearly billing drops substantially. Balancing personal bank reserves against potential disaster costs lets property owners secure lower monthly rates without risking complete financial hardship during sudden, catastrophic weather events.
-
What is the main benefit of building property coverage?
Securing building property coverage protects essential architectural structures, including load-bearing walls, foundations, roof systems, and plumbing lines. This financial safety net guarantees direct funding for major building repairs following severe storms. Preserving property equity prevents complete asset loss, allowing property owners to restore structural safety and maintain real estate market value without draining personal retirement savings.