Skip to content

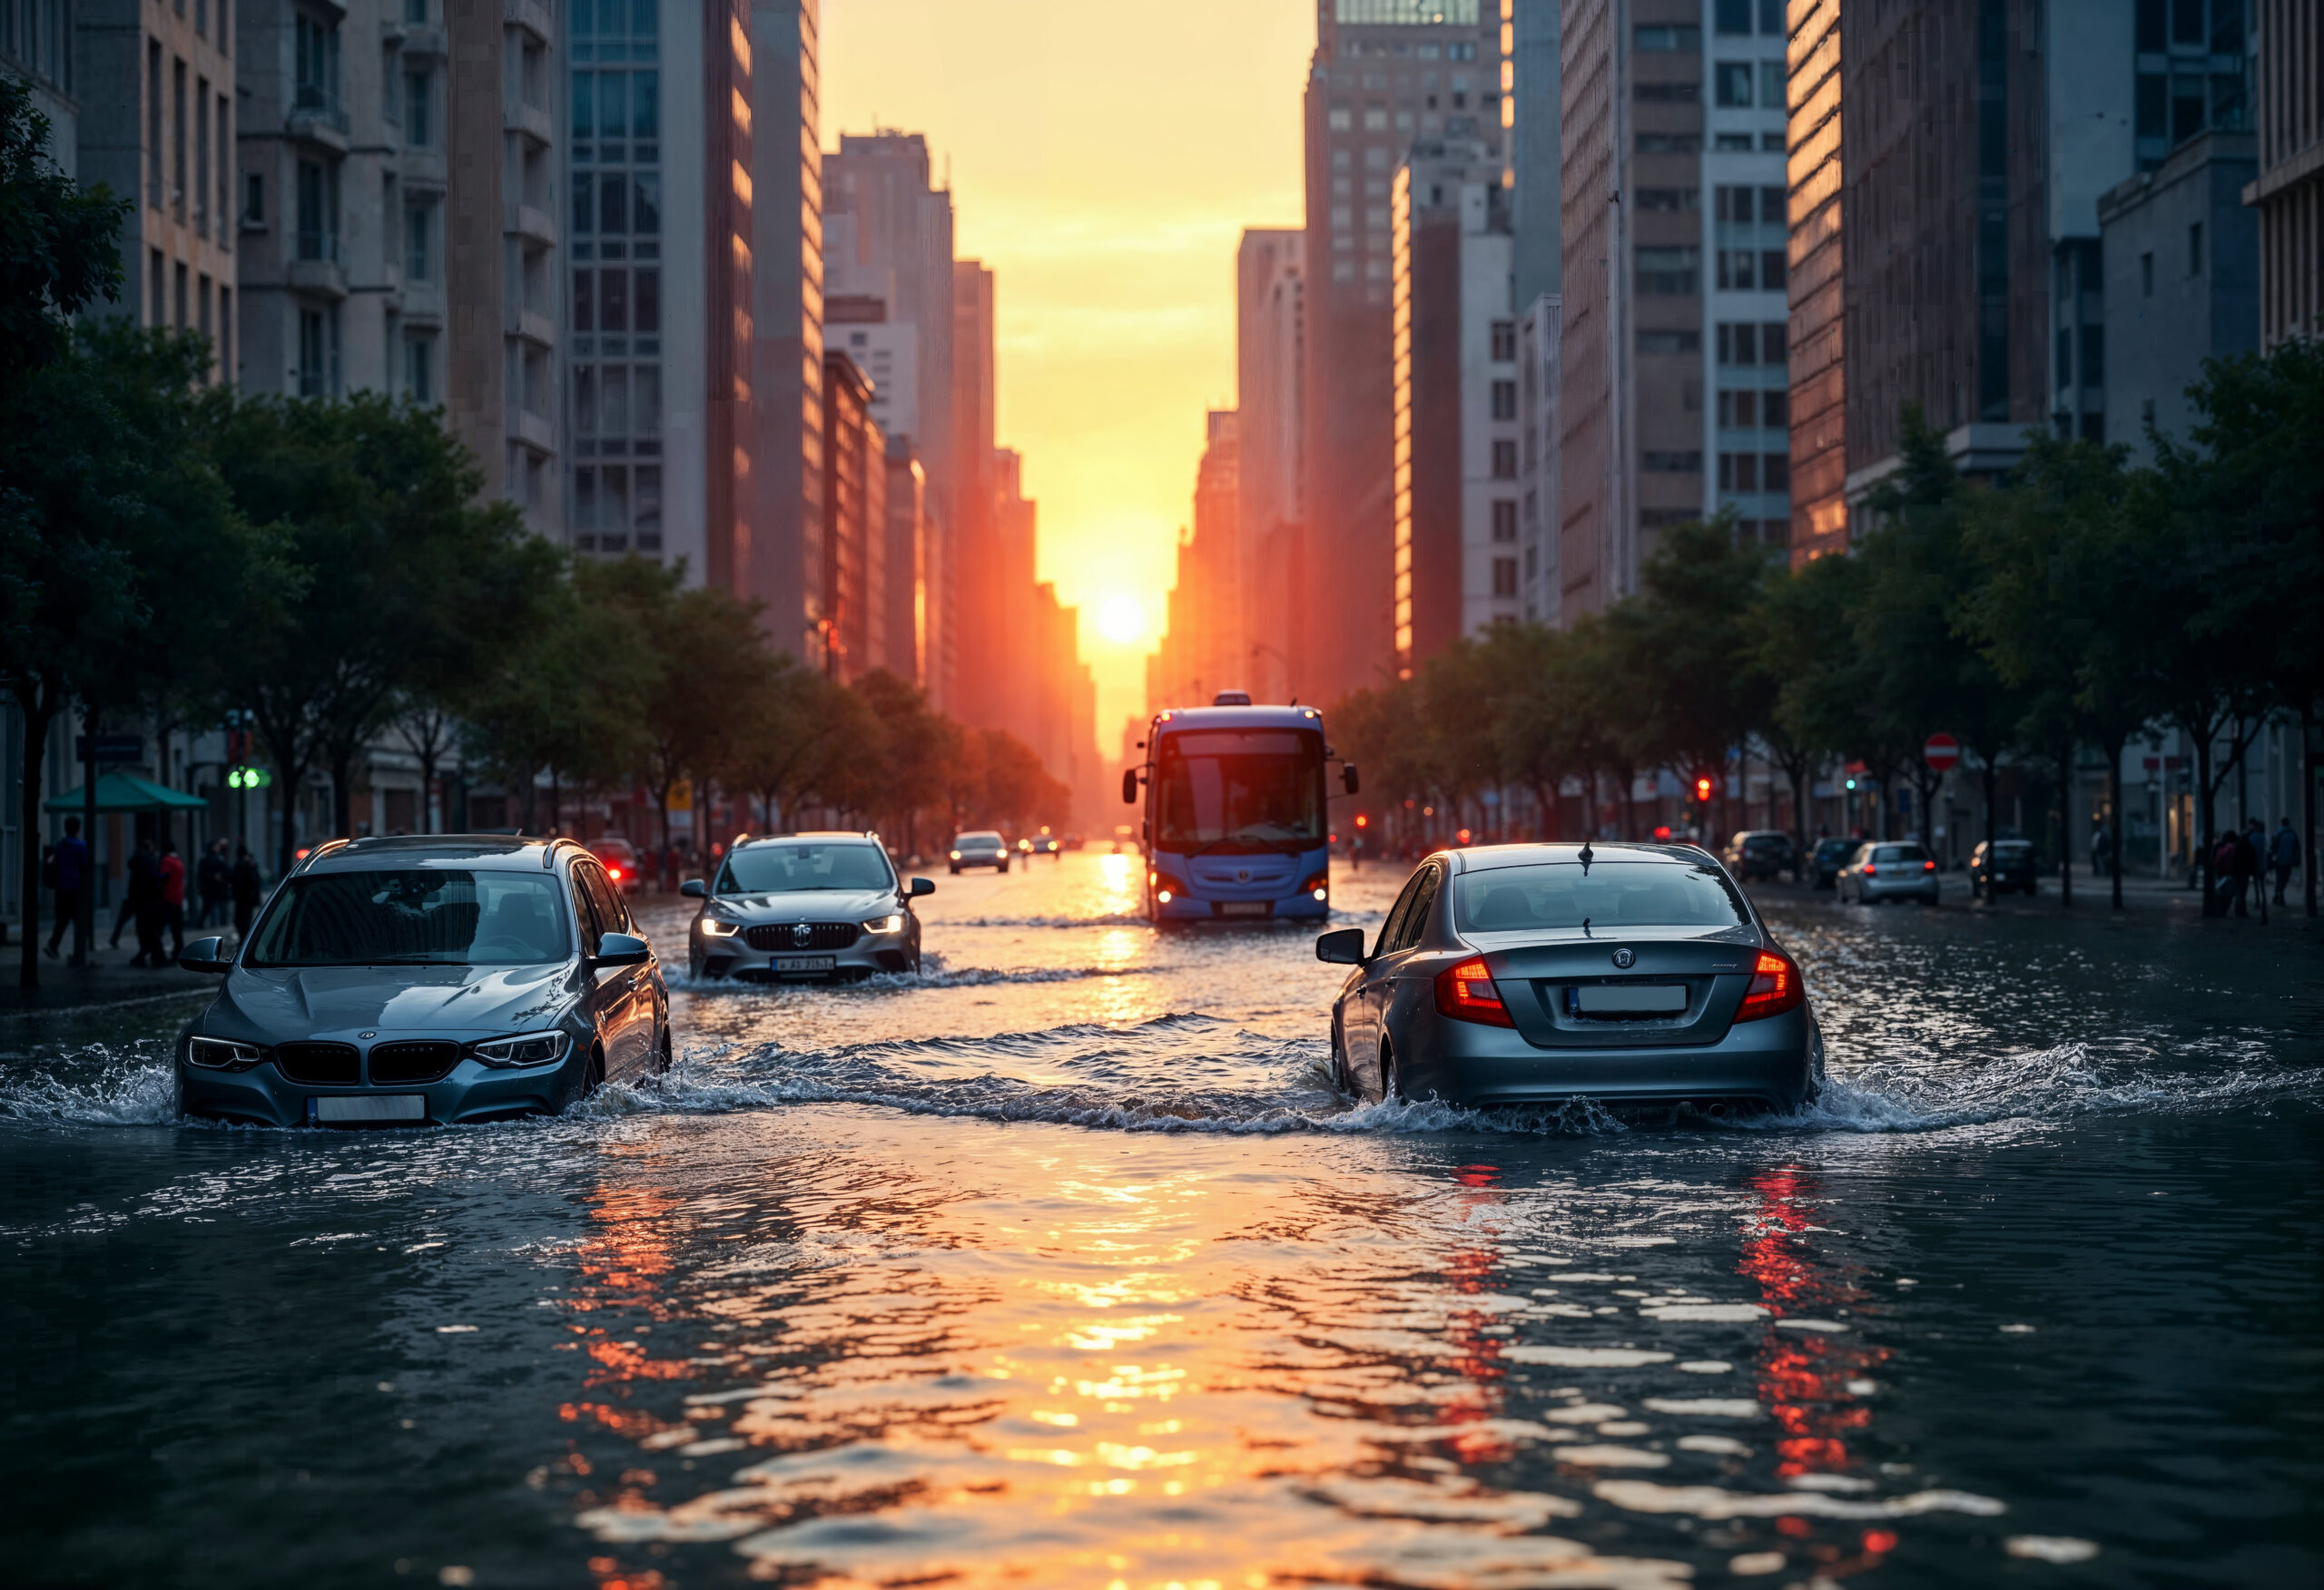
Securing dependable financial protection against rising waters requires a careful balance between price and coverage. Property owners often struggle to distinguish between a budget-friendly policy and one that leaves structural gaps exposed during a disaster. Finding a dependable flood insurance quote in Florida involves evaluating property elevation along with foundation engineering. Assessing local weather vulnerabilities and carrier reputation ensures proper coverage when severe storms hit. Flood Insurance HQ helps property owners review both federal programs and private coverage. This matches tailored policies to specific regional risks without sacrificing financial security.
What Key Factors Impact the Cost of Flood Coverage?
Insurance risk assessment relies on precise property metrics rather than broad regional estimates. Modern underwriting evaluations analyze individual building characteristics. These new systems review property features alongside traditional flood zone classifications to establish pricing.
- Building Elevation and Foundation Design: Structures built above base flood levels present reduced claims exposure. Foundation mechanics determine how water moves around a structure during peak surge events.
- Structural Material and Construction Quality: Concrete block and masonry construction tolerate moisture intrusion better than standard wood framing. Building durability leads to variations in potential repair costs and baseline pricing.
- Coverage Limits and Deductible Choices: Selecting higher out-of-pocket deductibles lowers ongoing expenses. Opting for maximum structural and contents limits increases total overall premiums.
Understanding these elements allows policyholders to address structural vulnerabilities directly. Homeowners can secure an affordable flood insurance quote while preserving complete property protection.
Ready to protect your property against unexpected water damage?
Get A Quote
Why Do Private Policies Offer Different Pricing Than NFIP Coverage?
Property owners in coastal areas historically depended entirely on the National Flood Insurance Program (NFIP) for water damage protection. The expansion of private independent markets provides alternative pricing structures. Private plans offer expanded coverage limits tailored to high-value properties.
The primary distinction stems from underwriting flexibility. Federal plans follow fixed government rating tables across wide geographies. Well-fortified homes in moderate zones often pay higher baseline costs under federal grids. Private underwriters evaluate dynamic weather models alongside hyper-local topographical surveys. They analyze specific property modifications to offer customized flood insurance quotes that mirror real-world risk.
Private plans frequently incorporate extended benefits omitted from standard federal policies. These enhancements include loss-of-use coverage for temporary relocation costs. Private carriers cover unattached outdoor structures like detached garages or sheds, offering contents limits above the federal cap. Comparing both avenues ensures home and business owners secure maximum protection at competitive baseline costs.
How Can Property Modifications Lower Annual Premium Costs?
Homeowners can reduce water damage risks and annual expenses by implementing targeted structural upgrades. Insurers reward proactive risk reduction with discounted pricing structures. Improvements reduce total claim severity during storm events.
Installing flood vents in enclosed areas allows rising water to flow through non-living spaces. This design balances hydrostatic pressure against foundation walls to prevent structural failure. Converting lower levels into non-habitable storage spaces or raising mechanical equipment lowers overall risk. Relocating main electrical panels, water heaters, HVAC compressors, and plumbing systems to higher platforms cuts potential repair estimates following a flood.
Documenting home improvements through a current elevation certificate provides insurers with physical proof of reduced risk. Presenting updated technical surveys during the underwriting process helps secure structural discounts. These measures lead to lower insurance premium obligations each year.
What Makes a Water Damage Policy Truly Dependable During a Claim?
An affordable policy holds little value if a carrier lacks the financial strength to process claims quickly. True policy reliability rests on a carrier’s financial stability. Clear policy language and responsive claims processing remain vital.
Evaluating financial strength ratings from independent rating agencies confirms that a carrier maintains sufficient capital reserves. Financial solvency ensures an organization honors high volumes of simultaneous claims without administrative stalls or payout delays.
Clear policy terms regarding structural definitions, contents valuation, and exclusions remain critical. Dependable policies explicitly detail how loss settlements are calculated using replacement cost value or actual cash value. Transparency prevents unexpected out-of-pocket expenses during property restoration. Clear terms, robust customer support, and dedicated adjusters ensure smooth claims processing when immediate assistance is needed most.

How Does Property Elevation Change Flood Insurance Eligibility?
Structural elevation serves as a primary metric used by underwriters to calculate water entry risk. A building’s height relative to local base flood levels determines both baseline policy terms and total flood insurance eligibility across public and private markets.
Properties constructed above established flood levels demonstrate minimal exposure to storm surges and localized flash flooding. Lower-risk structures qualify for preferred rates, expanded coverage terms, and lower baseline deductibles. Higher structures avoid strict underwriting restrictions that apply to older ground-level buildings.
Ground-level structures situated below established base flood elevations face strict underwriting criteria due to surge vulnerabilities. Federal programs guarantee coverage access regardless of height. Private carriers apply strict height thresholds before extending comprehensive terms or require specialized structural mitigation.
Is your home fully protected against severe weather events?
Contact Flood Insurance HQ Today
Finding Dependable Coverage for Your Property
Securing good financial protection means balancing realistic property risk with broad policy coverage. Working with experienced flood insurance providers helps property owners get expert guidance when choosing between federal programs and private coverage options. Looking at foundation designs, structural elevations, and changing weather patterns helps secure an accurate flood insurance quote without losing coverage quality. Flood Insurance HQ makes evaluating insurance simple by comparing top-rated policies, helping home and business owners protect their investments against unexpected storm damage. Therefore, finding the right coverage comes down to picking trusted flood insurance providers in Florida who can safeguard your home or business for the long haul.
Frequently Asked Questions
-
What factors dictate a flood insurance quote in Florida?
Location, base elevation, structural material, and foundation design determine a flood insurance quote in Florida. Underwriters analyze dynamic weather patterns, local drainage infrastructure, distance to coastlines, and selected deductible limits. Evaluating federal policies alongside private market options secures accurate, comprehensive coverage tailored directly to specific coastal or inland property risks.
-
How can a homeowner secure an affordable flood insurance quote?
Installing flood vents, raising HVAC equipment, and choosing higher deductibles help secure an affordable flood insurance quote. Maintaining an updated elevation certificate provides insurers with physical proof of reduced risk, lowering baseline annual premiums. Reviewing private market alternatives against standard federal programs unlocks additional savings for well-fortified regional properties.
-
What causes variations between different flood insurance quotes?
Underwriting metrics, structural limits, contents valuations, and loss-of-use additions create distinct flood insurance quotes. Federal programs rely on fixed regional rating grids, whereas private carriers utilize dynamic risk modeling and structure-specific data. Selecting replacement cost value instead of actual cash value coverage creates noticeable pricing variations across competing options.
-
Which factors influence annual flood insurance eligibility?
Base flood elevation, foundation structure, property usage, and regional zone classifications dictate overall policy parameters and flood insurance eligibility. Properties built above base flood levels qualify for broader terms and preferred private market rates. Ground-level or repetitively damaged structures utilize government-backed plans when private carrier criteria prove restrictive.
-
Why do policyholders switch flood insurance providers in Florida?
Property owners select alternate flood insurance providers in Florida to gain higher coverage limits, lower deductibles, or competitive rates. Private carriers offer flexible terms, including loss-of-use protection and unattached structure endorsements absent from standard federal policies. Partnering with specialized brokers provides direct access to top-rated carriers, ensuring robust storm protection.